Options Profit Calculator
Build any options trade, from a single call to an iron condor, and see its profit and loss at expiration and today, with breakevens, max risk and Greeks.
Quick examples
Market inputs
Legs
Leave a premium blank to use the model price shown in grey. Option quantity is in contracts of 100 shares; stock quantity is in shares.
Position
- Net debit
- Theoretical value now
- Max profit
- Max loss
- Breakevens
- Capital at risk
Position Greeks
- Delta
- Gamma
- Theta / day
- Vega / 1%
- Rho / 1%
P&L per position (x100 shares per contract)
- At expiration
- Today
Model estimates from Black-Scholes, not live quotes. Not financial advice. Options involve substantial risk.
How to use the options profit calculator
An options profit calculator shows what a trade can make or lose at every stock price, both at expiration and before it. Use it to check a trade before you place it.
- Enter the stock. Type the underlying price, the days to expiration and the implied volatility from your option chain.
- Pick a strategy. Choose a preset such as a long call or an iron condor, or build your own legs.
- Check the legs. Set each strike, quantity and premium. Leave the premium blank to use the model price.
- Read the results. The chart shows profit at expiration and today. The cards show breakevens, max profit, max loss and Greeks.
How options profit is calculated
Every option has a value at expiration called intrinsic value. Profit is that value minus what you paid, times 100 shares per contract.
| Position | Profit at expiration, per contract |
|---|---|
| Long call | (max(stock price minus strike, 0) minus premium) x 100 |
| Long put | (max(strike minus stock price, 0) minus premium) x 100 |
| Short call | (premium minus max(stock price minus strike, 0)) x 100 |
| Short put | (premium minus max(strike minus stock price, 0)) x 100 |
For spreads, straddles and iron condors the calculator adds every leg together at each price.
Worked example: a long call
A stock trades at $450. You buy one 455 call with 30 days left for $8.75.
- Cost and max loss: $8.75 x 100 = $875, if the stock ends at or below $455.
- Breakeven: $455 + $8.75 = $463.75 at expiration.
- If the stock ends at $480: ($480 minus $455 minus $8.75) x 100 = $1,625 profit.
- Max profit: unlimited, because a call keeps gaining as the stock rises.
Profit at expiration vs profit today
Before expiration an option still has time value, so the today line sits above the expiration line for a long option and below it for a short one. Time decay (theta) pulls the two lines together each day. A higher implied volatility raises option prices, and a drop in IV, common right after earnings, lowers them even if the stock does not move.
The Greeks in one line each
- Delta: how many dollars the position gains for each $1 the stock rises, in shares.
- Gamma: how fast delta changes as the stock moves.
- Theta: dollars gained or lost per day from time decay.
- Vega: dollars gained or lost for each 1 point change in implied volatility.
- Rho: dollars gained or lost for each 1% change in interest rates.
Assumptions and limits
Prices come from the Black-Scholes model with European exercise and no dividends. Implied volatility and the interest rate stay constant. Fees, the bid ask spread, early assignment and taxes are not included. Use the results as estimates, not quotes.
Need implied volatility for a strike? The free delayed option chain lists it for every strike. To find trade ideas, try Theta Farming.
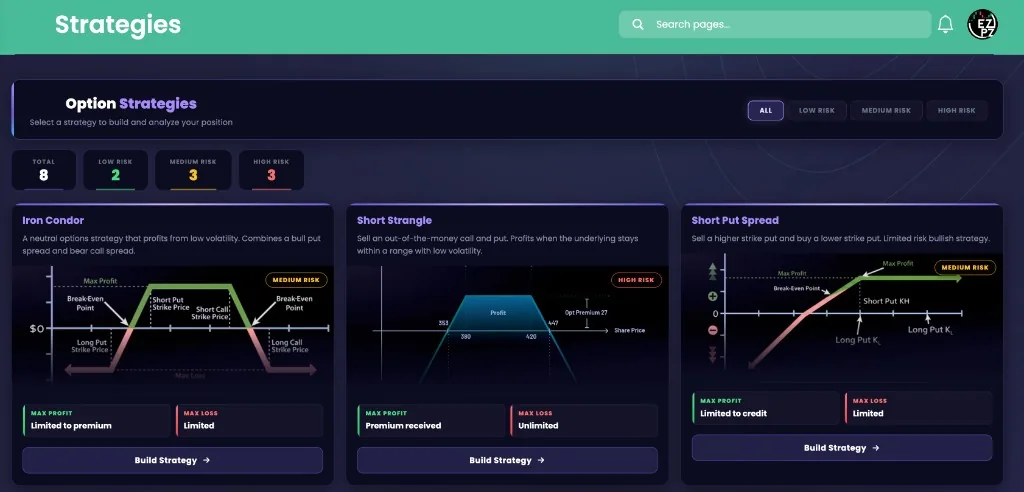
Build it on live data with EZPZ Strategies
This calculator uses the numbers you type in. When you want the same trade on a real ticker, EZPZ Strategies builds it from the live option chain: pick a strategy such as an iron condor or a short put spread, choose a ticker, and see the payoff, breakevens, max profit and max loss on today’s prices.