Learn Center
IV Rank Explorer
Where a stock's current implied volatility sits relative to its own history, used to judge whether options look cheap or expensive right now.
What is IV rank?
IV rank is where current implied volatility sits versus that ticker's own high and low. On EZPZ, IV Rank Explorer is one searchable name: Current IV (30D), IV Rank (1Y), IV Rank for Timeframe, and IV Percentile (1Y). Type e.g. SPY, then Go. Timeframe starts at 10 Days. It is not a buy or sell.
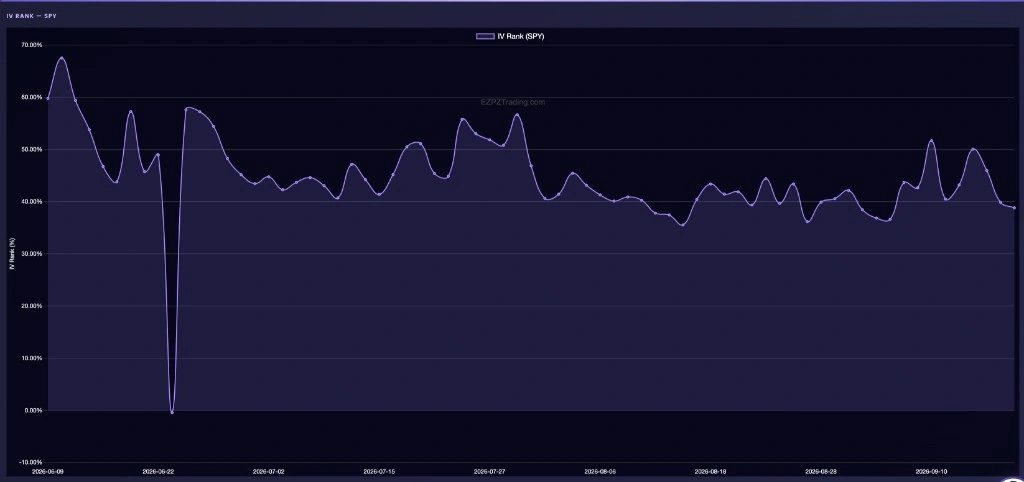
On EZPZ, the live page title is IV Rank Explorer. The eyebrow is Options Analytics. The ticker line starts on SPY plus last price. The screenshot uses SPYDY at $761.69. The subline is IV Rank Explorer, then Historical implied volatility rank and percentile. Placeholder is e.g. SPY. Go loads the name. Enter in that box also loads it. Timeframe starts at 10 Days. Choices are 10 Days, 20 Days, 30 Days, 50 Days, and 100 Days. The screenshot uses 100 Days. Eight cards sit under that bar. Current IV (30D) is first. IV Rank (1Y) is next. IV Rank for the selected Timeframe follows. IV Percentile (1Y) is the fourth card. High IV (1Y) and Low IV (1Y) sit on the second row, then High IV and Low IV for the same Timeframe. The chart title is IV Rank, then the ticker. The y-axis label is IV Rank (%). The legend is IV Rank plus the ticker. A dip on that line is a history point. It is not a forecast.
On EZPZ, this page is the 1Y versus Timeframe IV rank chart for any ticker you search. Historical Volatility is 10D through 90D realized Volatility versus Price, not IV Rank. Volatility Analysis is Volatility By Open Interest, Open Interest, and Implied Volatility Smile, not these rank cards. Ticker Explorer keeps Implied Volatility (30 D), IV Rank, and IV Percentile as one-symbol cards, not this history line. Largest Premium By Tickers has a High IV Rank leaderboard when you do not have a ticker yet. Top 20 Optionable ranks listed-option names by Vol. * Price and shows IV Rank on the row. Greeks is Call and Put Delta, Theta, and IV across five expiries, then Delta, Theta, Vega, and Gamma Maturity. Expected Move is the DEM and VEM band chart by expiration. Put to Call Ratio is the Intraday Put/Call Ratio chart of Traded PCR, OI PCR, and Sentiment PCR. Max Pain is Intraday Max Pain with O-Max Pain, P-Max Pain, and V-Max Pain. Gamma Exposure is the searchable strike table with Call Wall and Put Wall. GEX and DEX is the Intraday GEX and DEX chart pair with Gamma Flip. Spot Gamma and Delta is the ($) Open Interest versus ($) Volume bar pair with a Spot line. GEX Heatmap is the strike-by-expiration GEX grid with a GEX Details table. Greeks Heatmap is the strike-by-expiration grid with Gravity Magnet Score. Option Depth Flow is the searchable strike-by-time Bubble or Gradient chart. Market Maker Exposure is the SPX Flip Level chart with Call Wall, Put Wall, and Expected Move(VEM) and DEM. Market Cross Flow is the SPY, SPXW, and QQQ GEX grid next to candles. Open Interest Scan is the OI per Strike and OI per Expiration chart pair. Volume Scan is the Volume by Strike and Volume by Expiration chart pair. Index Trader is the index dashboard with Premium Traffic Lights. Market Wave is the Current Day chart of Net Call Premium versus Net Put Premium. Net Flow Graph is one ticker you search with Filter ticker, plus Cumulative Volume Delta. Historical Net Premium is the 15D Cumulative lookback with a daily table. 0DTE Graph is the same-day premium chart with Filter ticker. The 0DTE dropdown is the lock. Weekly-DTE Graph is the WTE chart of premium that expires by Friday. 7-DTE Graph is the 7DTE chart of premium in the next 7 days. Supply and Demand X-ray is the ITM Call and Put chart of Price, Supply, and Demand. Money Sentiment is Bought Ratio, Net Sentiment, and Netflow Graph for one ticker. Net Premium Heatmap is the strike-by-expiration grid of Net Premium for one ticker. Movers and Shakers Tide is that same chart job for about 18 mega-cap names. Option Chain is the listed book, where implied volatility sits on a contract row. Live Flow is the tape of prints. Unusual Activity keeps only large, sweep, and block prints. Unusual Activity Intraday is the session scan with a date range. $1M Plus Flow keeps only million-dollar premium. 0DTE Flow keeps only prints that expire today. SPX and SPY Flow locks the tape to SPX, SPXW, and SPY. Historical Volatility is 10D through 90D Volatility versus Price. Volatility Surface 3D is Raw Contracts and Smoothed Mesh for one ticker.
How IV Rank Explorer works on EZPZ
Search a ticker, leave Timeframe on 10 Days, then read IV Rank (1Y) next to IV Rank for that window. It is not a score. Most people start with Current IV (30D) and IV Rank (1Y). If those two feel quiet, switch Timeframe to 20 Days, 30 Days, 50 Days, or 100 Days and compare the period card with the 1Y card. Then read IV Percentile (1Y). High IV and Low IV on both rows are the range those ranks sit in. Do not treat SPY as a default thesis.
How this differs from Volatility Analysis
Volatility Analysis is three strike charts: Volatility By Open Interest, Open Interest, and Implied Volatility Smile. Each card has its own Strikes Min and Max plus an expiry. This page has no smile and no IV × OI. It is Current IV (30D), IV Rank (1Y), period IV Rank, IV Percentile (1Y), and High IV / Low IV, then one IV Rank line. Use Volatility Analysis when you want IV by strike. Use Historical Volatility when you want 10D through 90D versus Price. Use this page when you want 1Y rank next to the Timeframe you pick. Use Ticker Explorer when you want Implied Volatility (30 D), IV Rank, and IV Percentile beside quote and unusual activity. Use Largest Premium By Tickers when you want the High IV Rank list. Use Top 20 Optionable when you want IV Rank on a Vol. * Price row. Use Greeks when you want Call IV Distribution across five expiries. Use Expected Move when you want DEM versus VEM. Use Put to Call Ratio when you want Traded PCR. Use Max Pain when you want V-Max Pain. Use Gamma Exposure when you want Call Wall and Put Wall. Use GEX and DEX when you want Gamma Flip. Use Spot Gamma and Delta when you want ($) Open Interest versus ($) Volume. Use GEX Heatmap when you want pinning versus volatility cells. Use Greeks Heatmap when you want Gravity Magnet Score. Use Option Depth Flow when you want strike by time. Use Market Maker Exposure when you want SPX Flip Level. Use Market Cross Flow when you want SPY, SPXW, and QQQ side by side. Use Open Interest Scan when you want standing contracts. Use Volume Scan when you want Call and Put volume. Use Index Trader when you want traffic lights. Use Market Wave when you want Current Day Net Call Premium versus Net Put Premium. Use Net Flow Graph when you want Filter ticker plus Cumulative Volume Delta. Use Historical Net Premium when you want the 15D table. Use 0DTE Graph when you want same-day premium. Use Weekly-DTE Graph when you want Friday. Use 7-DTE Graph when you want the next 7 days. Use Supply and Demand X-ray when you want Price, Supply, and Demand. Use Money Sentiment when you want Bought Ratio and Net Sentiment. Use Net Premium Heatmap when you want the strike-by-expiration grid. Use Movers and Shakers Tide when you want the 18-name basket. Use Option Chain when you want IV on a contract row. Use Live Flow when you want the prints.
Anatomy of the cards and chart
You do not need every card on every session. Use the tabs if you want a map of the fields.
The first row is Current IV (30D), IV Rank (1Y), IV Rank for Timeframe, and IV Percentile (1Y).
| On the page | What you are looking at |
|---|---|
| Current IV (30D) | Thirty-day implied volatility for the ticker you loaded. The screenshot prints 12.49% on SPYDY. |
| IV Rank (1Y) | Where that implied volatility sits versus this ticker's own one-year high and low. The screenshot prints 38.81%. |
| IV Rank (10D) | The same rank idea on the Timeframe you picked. The label becomes IV Rank (20D), (30D), (50D), or (100D) when you change Timeframe. The screenshot uses 100 Days and prints 57.36%. |
| IV Percentile (1Y) | How many days in the one-year window closed with implied volatility below today. The screenshot prints 6.80%. |
The second row is High IV (1Y), Low IV (1Y), then High IV and Low IV for the selected Timeframe.
| On the page | What you are looking at |
|---|---|
| High IV (1Y) Low IV (1Y) | The one-year implied volatility high and low behind IV Rank (1Y). The screenshot prints 26.82% and 3.39%. |
| High IV (10D) Low IV (10D) | The high and low inside the Timeframe you picked. Labels follow 10D, 20D, 30D, 50D, or 100D. The screenshot uses 100 Days and prints 19.25% and 3.39%. |
The card title is IV Rank, then the ticker. The y-axis label is IV Rank (%).
| On the chart | What you are looking at |
|---|---|
| IV Rank | One line of historical IV Rank. The legend adds the ticker in parentheses. Hover a date for IV Rank as a percent. |
| IV Rank (%) | The y-axis. The scale is a percent, not a dollar price. |

Header and Timeframe
- Search / Go: Type a ticker. Placeholder is e.g. SPY. Go loads the name. Enter also loads it.
- Options Analytics: The eyebrow above the ticker line.
- IV Rank Explorer: The subline under last price, then Historical implied volatility rank and percentile.
- Timeframe: 10 Days starts selected. Choices are 10 Days, 20 Days, 30 Days, 50 Days, and 100 Days.
Controls on this page
The header has search, Go, and Timeframe. Use those controls to change the window. Do not treat them as a score.
- Search / Go: Load another name. Placeholder is e.g. SPY.
- Timeframe: 10 Days starts selected. Options are 10 Days, 20 Days, 30 Days, 50 Days, and 100 Days.
How people actually use it
Read Current IV (30D), then IV Rank (1Y)
Check the ticker line. Then read Current IV (30D) next to IV Rank (1Y) before you change Timeframe.
Compare the period card with 1Y
Leave Timeframe on 10 Days first. If you want a wider window, pick 20 Days, 30 Days, 50 Days, or 100 Days and compare IV Rank for that label with IV Rank (1Y).
Check percentile when rank looks loud
If IV Rank (1Y) sits far from IV Percentile (1Y), you are looking at two clocks. Rank uses the high and low. Percentile counts days.
Use it next to smile and the tape
This page is rank history. Open Volatility Analysis if you want IV by strike. Open Live Flow if a spike makes you want the prints.